QJSA requirement and the Solo 401k
To protect spouses of retirement plan participants, the Retirement Equity Act (REA) was created in 1984. This was to ensure that the surviving spouse received the retirement benefits after a plan participant’s death.
REA established the Qualified Joint and Survivor Annuity (QJSA) as the default option for some plans.
A QJSA is “when retirement benefits are paid as
- a life annuity (a series of payments, usually monthly, for life) to the participant and
- a survivor annuity over the life of the participant’s surviving spouse (or a former spouse, child or dependent who must be treated as a surviving spouse under a QDRO) following the participant’s death.” (IRS)
Some plans are subject to QJSA, and some can be exempt from QJSA.
Some plans are always subject to QJSA
Certain retirement plans, like a defined benefit and money purchase plans, must provide a QJSA to all married participants. This must be provided unless the married participant (and their spouse, if applicable) have written consent to another form of benefit payment.
If a plan is subject to QJSA, then the married participant must have spousal consent for all distributions and loans from the plan.
Some plans may not be subject to QJSA
As a profit sharing 401k plan, the Solo 401k can be exempt from QJSA, if:
- It requires the death benefit to be paid in full to the surviving spouse unless the spouse has consented to another beneficiary, and
- It does not offer a life annuity benefit under the plan, and
- It does not contain a direct transfer from another plan that is subject to QJSA
If the Solo 401k satisfies all of the above requirements, the plan falls under “REA safe harbor” and is exempt from QJSA.
Under REA safe harbor, spousal consent is not required for distributions from the plan.
Is my Solo 401k exempt?
Your plan may be marked as subject or not subject to QJSA. By default, the plan is marked as not subject to QJSA.
However, if your plan does contain a direct transfer from another plan that is subject to QJSA (e.g. you transferred funds from a defined benefit plan into your Solo 401k), then it must be marked as subject to QJSA for those funds.
Those funds should be kept in their own account and tracked by you since they are subject to QJSA.
Check your plan documents
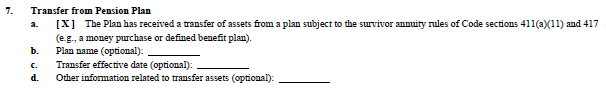
- If you have transferred funds from a plan that is subject to QJSA, you should have this checked in your plan documents
- Review your Adoption Agreement, Section F
- 7.a. should be checked as below
- Contact Sense Financial to update the plan if the above is not marked in your plan documents